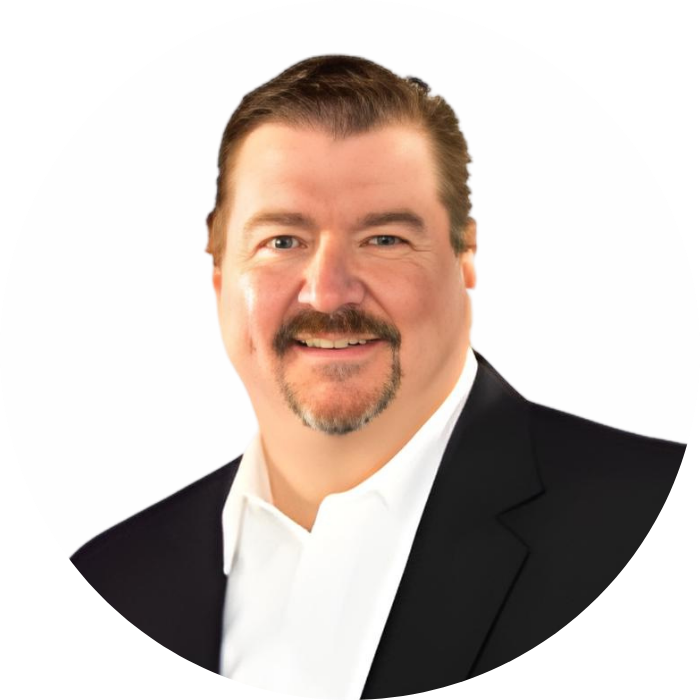
MARINE VETERAN • MORTGAGE VICE PRESIDENT
Everything You Need to Know
VA HOME LOAN BENEFITS
Straight answers on the VA home loan benefit you earned. Check eligibility, estimate payments, understand funding fees, and explore options for buying again or refinancing.
Independent educational resource • Not affiliated with or endorsed by the U.S. Department of Veterans Affairs
Your benefits. Your questions.
You served. The homebuying process shouldn't require learning another language. Pick a starting point below.
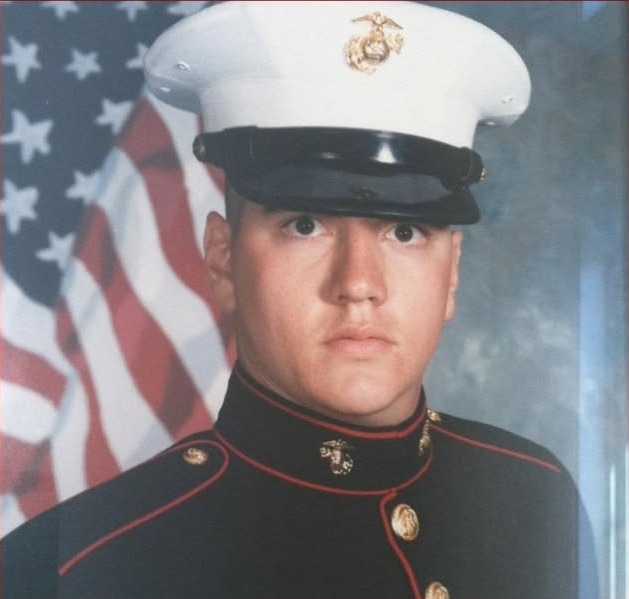
THEN • U.S. MARINE CORPSFrom one veteran to another
Service first. Straight answers always.
David Mulkey is a United States Marine Corps veteran and Mortgage Vice President with Presidential Bank Mortgage. This free resource is designed to help fellow veterans and military families understand VA loan benefits, spot common surprises, and take their next step with confidence.
Start with the official VA resources, try the calculators, and reach out if you want a real person to help make sense of your options.
Meet David Mulkey and get in touch →START HERE / Your path to the keys
Your VA homebuying roadmap.
First home or fifth, you don't have to learn mortgage jargon to get started. Here's the order of operations, with the important surprises called out before they become expensive.
Check your VA eligibility
Review service requirements and request your Certificate of Eligibility (COE). It's proof of basic benefit eligibility, not a loan approval.
Request a COE at VA.gov ↗Know your real budget
Estimate the payment, funding fee, and money you may need for inspections, appraisal, prepaids, and closing costs. Zero down does not mean zero cash.
Try the payment calculator →Get preapproved
Have a lender review income, credit, debts, and remaining entitlement, especially if you've used the benefit before.
Understand repeat use →Shop with a VA-ready team
Choose a VA-experienced agent and pay attention to property conditions and condo-project approval before writing an offer.
See common homebuying questions →Protect the deal
Understand the VA appraisal and hire your own home inspector. Avoid new debts or major financial changes before closing.
Learn what to watch for →Close, move in, use your benefits
Review your final costs and occupancy plans, then check property-tax benefits, possible fee refunds, and future VA loan options.
Explore overlooked benefits →One surprise worth avoiding: “zero down” ≠ “zero cash.”
A qualified VA purchase may require no down payment, but there can still be earnest money, a private inspection, a VA appraisal, title or lender charges, prepaid taxes and insurance, and possibly buyer-agent compensation. Some amounts may be credited or negotiated. Your Loan Estimate and Closing Disclosure determine the actual figures. Standard purchase closing costs generally cannot be added to the VA loan; an eligible VA funding fee can be financed.
See VA's official closing-cost guidance ↗Your VA toolkit
Real answers. Useful numbers. No runaround.
Your service history and COE matter, but so do your goals, costs, and options. These tools help you prepare the right questions before taking the next step.
Purchase a home
Estimate principal, interest, taxes, insurance and how the VA funding fee affects your loan.
Run the payment calculator →Understand eligibility
Go straight to official VA pages for COE requests, prior use, and basic eligibility.
Check the resources →Refinance an existing VA loan
Compare possible monthly payments and closing costs for a VA streamline IRRRL.
Explore refinancing →01 / Buying a home
Your VA mortgage payment, explained.
Change the numbers below to explore a sample home purchase. The rate is an editable illustration, not a rate quote. Results update instantly in your browser.
Set up your scenario
All entries stay on your device. Enter amounts without dollar signs or commas.
Estimated monthly housing payment
Funding-fee exemption status may need confirmation. Other closing costs, prepaid expenses and escrow setup are not included. Mortgage insurance is generally not required for VA loans.
02 / Funding fee & exemptions
A funding fee can change the math. An exemption can, too.
VA purchase funding-fee percentages depend on first versus subsequent use and the size of the down payment. The calculator above applies these published tiers. Review the VA's official guidance ↗
2.15%
Example standard purchase-loan funding fee rate when no exemption applies.
3.30%
Reduced to 1.50% with 5% to under 10% down, or 1.25% with at least 10% down.
0%
Some borrowers receiving or eligible for VA service-connected disability compensation, among other categories, may be exempt. It is not limited to 100% ratings.
Additional savings and benefits
Two veteran benefits that are easy to overlook.
Your VA home loan benefits don't end with the payment calculator. These official VA resources can help you ask about potential property-tax savings and funding-fee refunds.
Could I qualify for a veteran property-tax exemption?
Some states and local governments offer property-tax exemptions or reductions to eligible veterans, including certain veterans with service-connected disabilities. Rules and application deadlines vary.
Start with your state, then confirm details with your state veterans agency and your local county tax assessor. Don't enter a reduced tax amount in the calculator until you've confirmed the benefit applies to you.
Explore veteran tax benefits by state at VA.gov ↗Can I get my VA funding fee refunded after closing?
Possibly. If you're later awarded qualifying VA disability compensation, you may be entitled to a refund when its effective date predates your VA loan closing. Receiving a rating after closing alone does not automatically qualify.
VA says it automatically reviews qualifying retroactive awards. If you think a refund was missed, contact your lender or VA Home Loan representatives at 877-827-3702. Don't send disability documents through this website.
Read the VA's funding-fee refund guidance ↗03 / Official VA resources
Your Certificate of Eligibility starts with the VA.
A COE documents basic eligibility based on military service or qualifying status. It is not a mortgage approval. For a COE or benefit record, use official VA websites rather than sharing service records on this page.
04 / Prior use & entitlement
Used your VA loan before? That doesn't end the story.
You may be able to use the benefit more than once. But remaining entitlement, a loan still outstanding, a previous sale, and possible restoration all change the answer. Full entitlement is not an unlimited approval.
Review your COE
It shows prior loans charged to entitlement, which is the starting point for figuring out what's available.
Full or remaining?
With full entitlement, VA generally imposes no guaranty loan limit. With partial entitlement, local limits and entitlement usage may affect down payment needs.
Review the scenario
A lender can help evaluate the COE, property, price and qualification. No calculator should claim an approval from entitlement alone.
05 / Refinance watch
Considering a VA Streamline Refinance?
The Interest Rate Reduction Refinance Loan (IRRRL) can help eligible borrowers with an existing VA-backed loan pursue lower payments or move from an adjustable to a fixed rate. It isn't a cash-out loan, and it's not right for everyone.
Compare a refinance scenario
Use your actual current principal-and-interest payment, not your total payment with taxes/insurance. Try a hypothetical new rate and closing costs.
Estimated new monthly principal & interest
*Illustrative total costs divided by P&I savings. This is not the VA statutory 36-month recoupment calculation, which excludes or treats certain fees differently. Taxes/insurance and remaining term aren't compared here. No loan approval or rate offer is implied.
An IRRRL generally refinances an existing VA-backed home loan. The property must be one you currently live in or previously occupied.
Exemptions can apply; this fee can often be financed alongside permissible closing costs.
VA IRRRL rules include at least six monthly payments and a 210-day seasoning threshold tied to the original loan's first payment due date.
Rate reductions, fee recoupment, closing costs and your remaining loan term affect whether refinancing makes sense.
Myths, facts & next steps
Questions worth asking.
Do I need a 100% disability rating to be exempt from the funding fee?
No. Qualifying VA service-connected disability compensation can support an exemption at ratings below 100%. Several additional categories can qualify. Verify your specific exemption before closing. VA guidance ↗
Does a COE mean I'm approved to buy?
No. A COE addresses basic VA benefit eligibility. A lender also reviews income, credit, debts, occupancy, property eligibility and valuation.
Can I buy with no down payment?
Often, qualified borrowers with enough entitlement can, but remaining entitlement and appraisal results may change the required down payment. Zero down does not mean zero closing costs.
Can I use the VA benefit more than once?
Potentially yes. Prior loans, remaining entitlement and possible restoration matter. A lender can review your COE and specific circumstances.
Can an IRRRL give me cash back?
An IRRRL is generally designed to refinance an existing VA-backed loan for rate or payment benefits, not provide cash-out proceeds. Ask about the separate VA cash-out refinance program if you need to access equity.
What happens to my information on this website?
These calculators run locally in your browser. They do not upload inputs, create an account, or send financial data to David. Text, call, email and Apply Now links open separate apps or services only after you choose them.
Can I receive a veteran property-tax exemption?
Depending on your state and local rules, you may qualify for a property-tax exemption or reduction. Eligibility, application deadlines and qualifying disability status differ by jurisdiction. Confirm with your state veterans agency and county assessor. VA state-by-state tax resources ↗
Can my VA funding fee be refunded if I receive disability compensation after closing?
Sometimes. VA generally looks to whether your qualifying disability compensation effective date was before the date your VA loan closed. A post-closing rating by itself does not establish refund eligibility. If you suspect a missed refund, ask your lender or VA Home Loan program at 877-827-3702. VA funding fee refund explanation ↗
Can I buy a condominium with a VA loan?
Yes, when the condominium development meets VA approval requirements. Check the official VA condo report search ↗ before you get too attached to a unit. If the project isn't listed as approved, ask your lender about the VA review process; it is not an automatic no, but it can take additional time. Approval is for the project, not just an individual unit.
Is a VA appraisal the same thing as a home inspection?
No. A VA appraisal considers value and minimum property requirements; it is not a comprehensive inspection of systems and condition. Get an independent home inspection to evaluate the home before you commit. VA guidance ↗
What if the VA appraisal comes in below the purchase price?
You may be able to negotiate the price, request a reconsideration of value through your lender, or explore paying a difference out of pocket. Review the VA escape clause and your purchase contract with your agent and lender before deciding what happens next. A low appraisal does not always mean you must pay the gap.
Do I need perfect credit to qualify for a VA loan?
No. VA does not set one universal minimum credit score for every VA-backed purchase loan. Individual lenders review credit and may impose their own standards. Income, debts, residual income, and the rest of your application also matter.
If I already have a VA loan, can I use the benefit again?
Sometimes, yes. Existing VA loans may leave some entitlement available, and entitlement may be restored in qualifying situations. Your COE and prior loan details are the right starting point. See the entitlement overview →
What should I avoid doing after preapproval?
Before closing, talk to your lender before taking on new debt, opening credit accounts, changing jobs, moving large unexplained deposits, or making major purchases. Any of these may affect final qualification, even after preapproval.
Real help when you want it
Questions about your VA benefits? Ask a fellow veteran.
I'm David Mulkey, a Marine Corps veteran and Mortgage Vice President with Presidential Bank Mortgage. Whether you're buying your first home, checking a funding-fee exemption, or considering a VA streamline refinance, I'll help you understand the numbers and the options.
Everything is optional. Your calculations stay private unless you choose to share information yourself. Apply Now opens Presidential Bank Mortgage's separate application service.